Client money, with a second pair of eyes.
TrustGuard holds client funds in ledgers per client and per matter, checks every trust action before money moves, and keeps the approvals and reconciliations your bar rules expect you to be able to show.
The rules TrustGuard enforces
Enforced by the application for every trust action — not left to a checklist.
The person who requests a transfer, refund or disbursement cannot be the person who approves it.
High-risk adjustments need approval from two different attorneys or owners.
Money held for one client or matter cannot be used to cover another's.
Ledger entries are corrected by reversal, not by editing history, and every approval is recorded with who and when.
The bank statement balance, the trust account and the sum of client ledgers are compared and signed off. The statement balance is entered from the bank statement.
Classified first. Then held, then released.
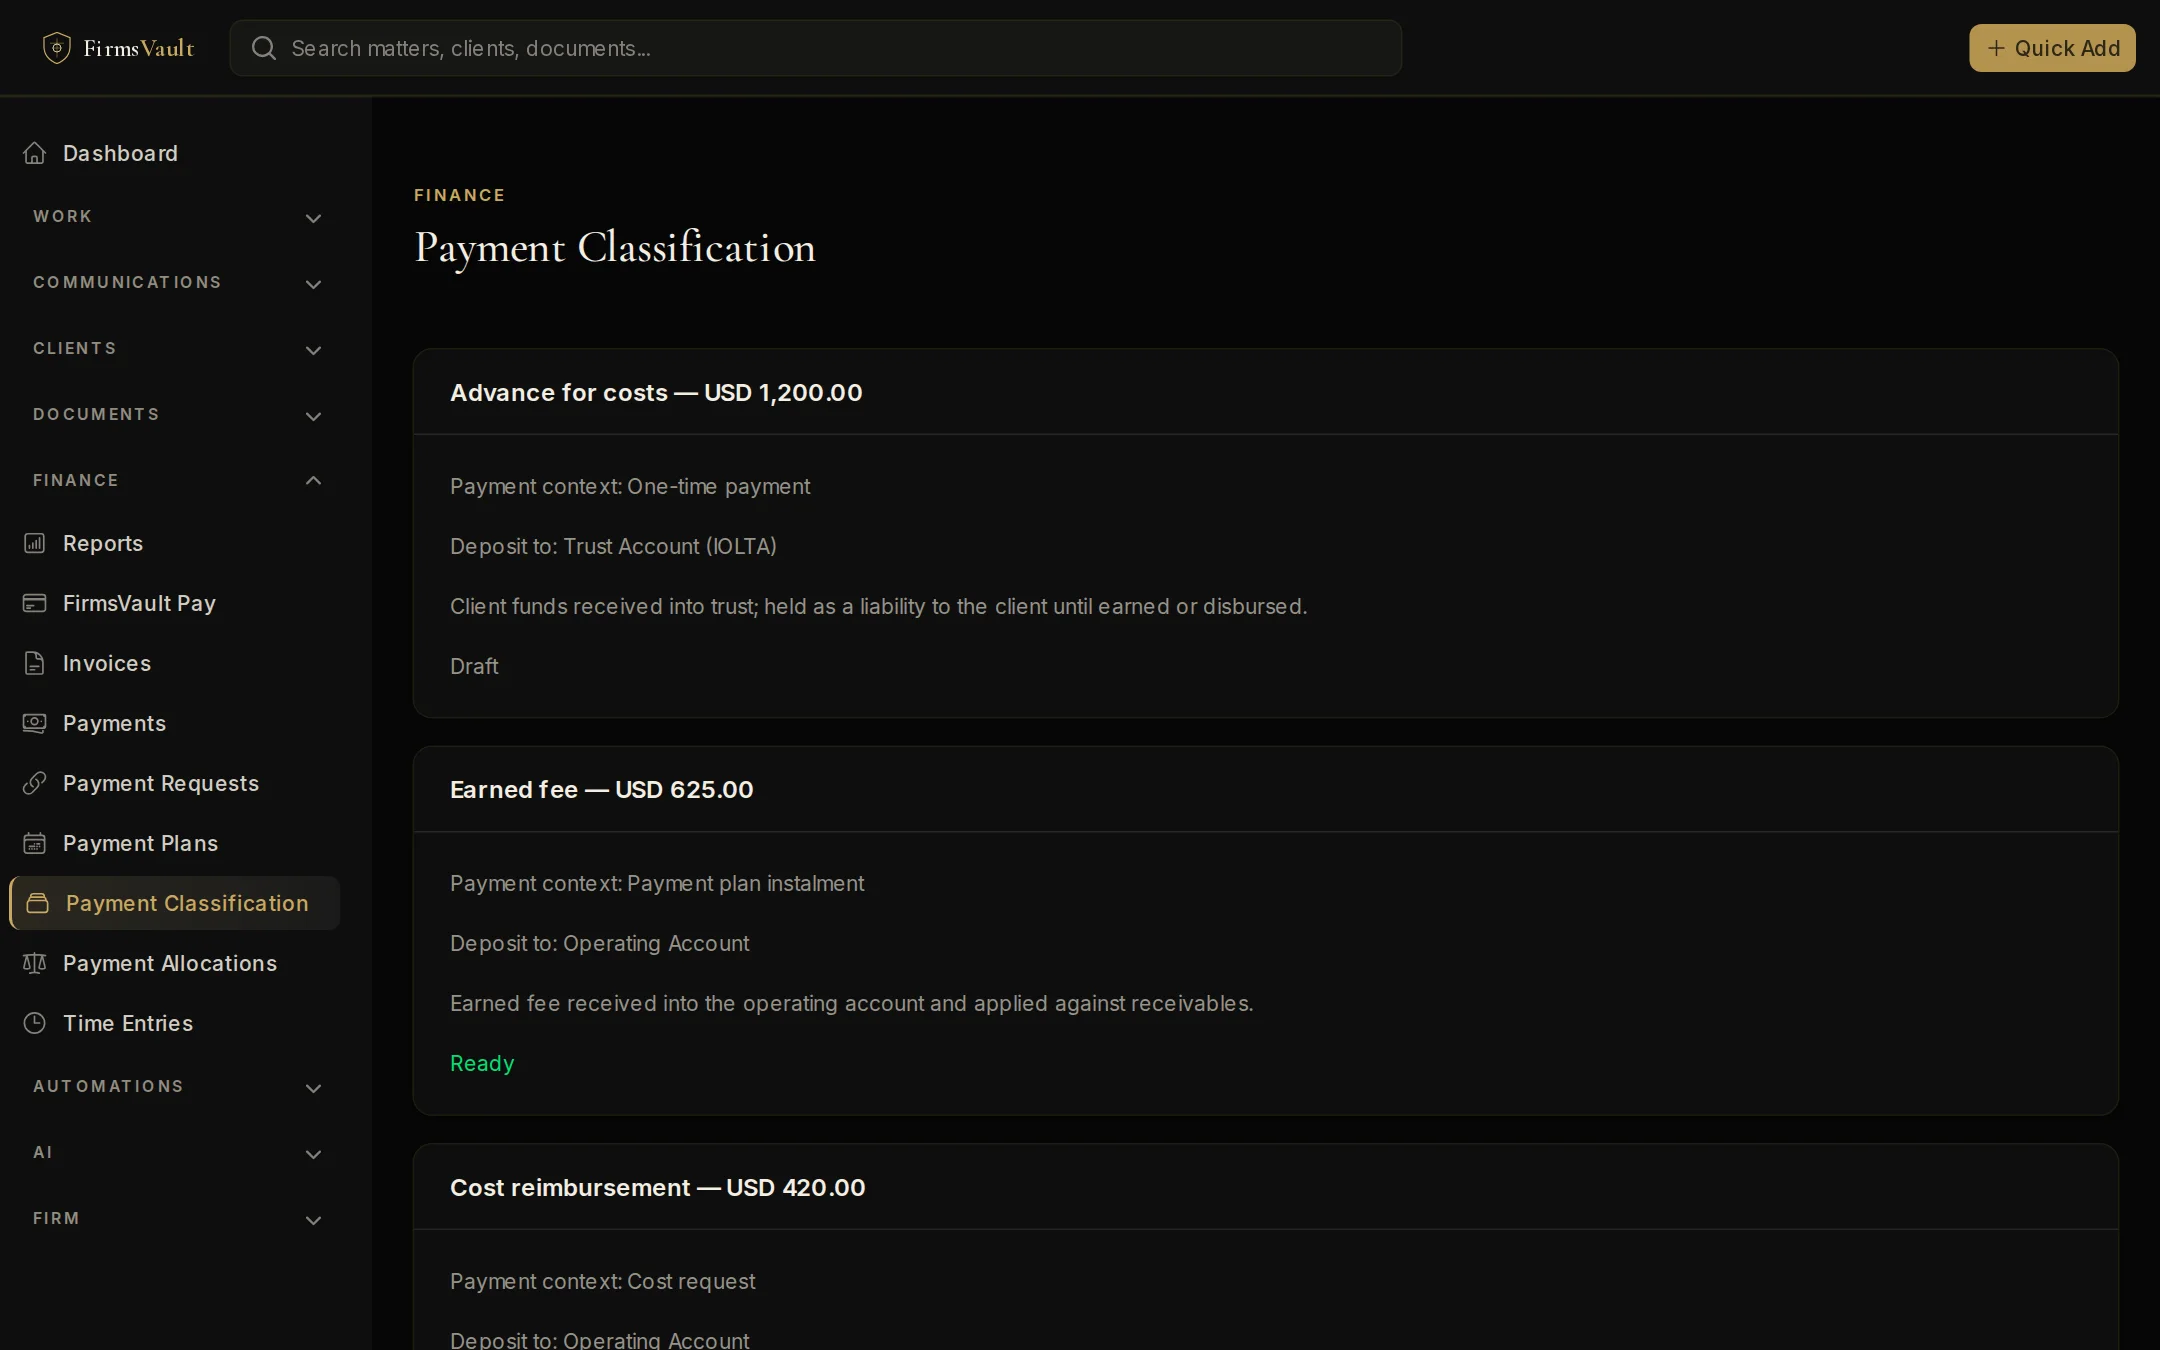
A payment is classified deliberately — by a person, before money moves — as an earned fee, trust deposit, retainer, cost reimbursement or payment-plan installment. Client funds are then held on the client's ledger, and a disbursement waits for someone other than the person who asked for it.
- Review status on every classification
- Approval recorded with who and when
- Three-way reconciliation with sign-off
Built for how trust money actually moves.
Deposits, fee transfers, cost reimbursements, disbursements to third parties and refunds each have their own request and approval path, and each posts to the right client ledger.
Your rules, your jurisdiction
Trust accounting rules differ by state. TrustGuard is switched on per firm once its trust accounts and jurisdiction are set up, and your firm remains responsible for compliance with its own bar's requirements. Taking card payments directly into a trust account is not enabled by default.
See FirmsVault with your own matters in mind.
A walkthrough shaped around your practice, your team and how you handle client money. No preparation needed.